
How the Soldier Field Lease Actually Works
Start with the counterparty, because it determines who has to sign off on any change. The Bears' stadium arrangement runs through the Chicago Park District, not the City of Chicago. That distinction is procedural and practical: a renegotiation, an extension, or an exit tied to the stadium premises is a Park District board action, not a City Council vote. If you see a report framed as "the city and the Bears" working out terms, treat that as shorthand until you find the amendment or board minutes naming the Park District as the party acting. The check is simple: pull the document, read the signature block and the approving body, and match the actor to the remedy.
Next, understand what an option year is before you read any deadline coverage. An option year is a unilateral extension right: the tenant can lock an additional year at pre-set terms without reopening the whole deal. That is why the exercise date carries more weight than the base term in coverage of the 2026 decision. The base term tells you where the team currently stands; the option tells you whether the team can hold that position without a fresh bargain. When you verify this, look for the clause that says who may exercise, what form the notice takes, and whether the terms are fixed by the existing instrument or subject to later agreement. If the terms are subject to later agreement, it is not a clean option year in the ordinary sense.
A stadium lease is not a normal commercial lease, and the difference matters most at the exit. A typical office or retail tenant can often plan around a notice period, a security deposit, and a remaining-rent exposure that a landlord must mitigate. A public stadium owner has a harder problem: the asset is specialized, the replacement tenant pool is thin, and the public owner carries the political and fiscal cost of an empty venue. That is why stadium leases commonly embed exit penalties through a buyout schedule or a remaining-rent formula. The mechanism is the point here, not any particular figure: the owner is trying to make departure expensive enough that the tenant internalizes the cost of leaving a purpose-built facility.
That structure explains why the rent line and the exit line do different work. Rent is the recurring operating term; the exit provision is the constraint on the decision itself. In a standard commercial setting, a tenant might compare month-to-month occupancy costs against moving costs. Here, the relevant comparison is between continuing under the pre-set terms and triggering a negotiated damages mechanism that the public owner designed to protect against precisely this kind of departure. Before accepting a characterization of either number, find the operative clause and read the defined terms around it.
Use this verification rule before any lease figure becomes part of your reasoning: pull the actual Park District lease amendment or board minutes and verify the number against at least two independent records. One record may be the amendment itself; another may be the board packet, agenda item, or minutes reflecting approval. If the reporting gives a figure without pointing to either, hold it as reported rather than established. The mechanism is stable — counterparty, option structure, exit protection — but the figures are volatile until the documents say otherwise.
The Evidence: Three Numbers That Converge
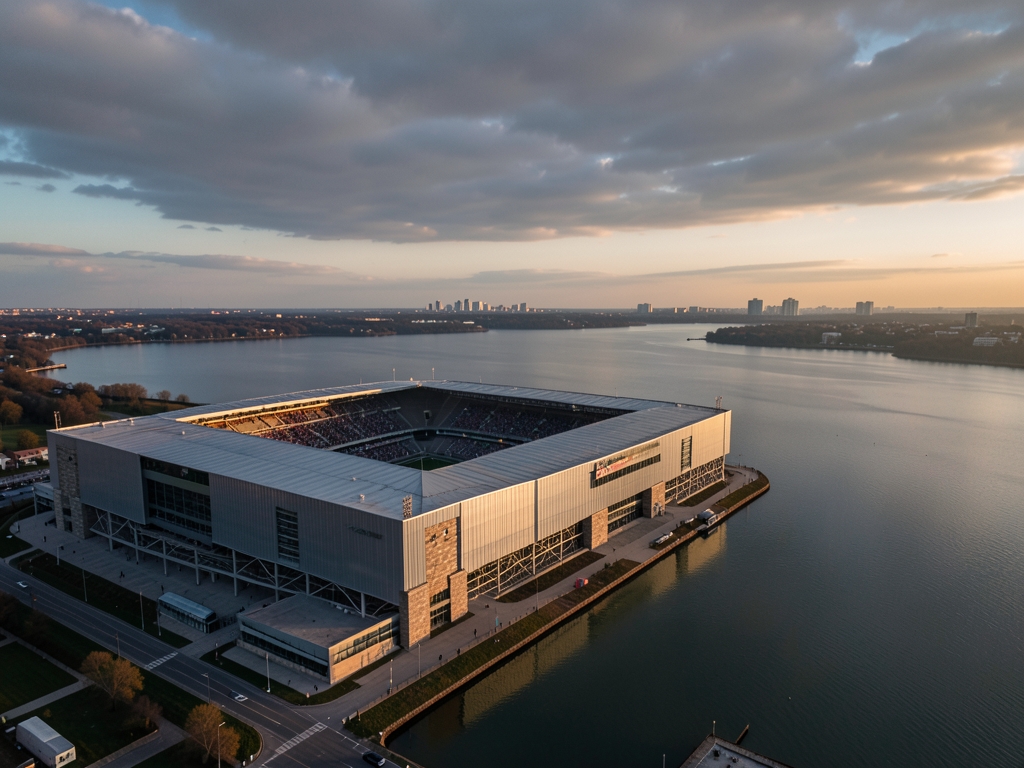
Three figures sit at the center of the public record, and none of them should be treated as final until you have pulled the underlying Chicago Park District lease amendment or board minutes and confirmed the number against at least two independent reports. The first is the break estimate: Chicago Tribune reporting by Bill Ruthhart put the cost of the Bears walking away from Soldier Field at nearly $90M. That is the hardest number in the public record because it is framed as an exit cost, not an operating expense. It is also the figure most likely to be quoted without its assumptions, so treat it as a reported estimate until the amendment language or a board packet shows the actual formula.
The second figure is the reported annual rent of roughly $6.5M. That number is useful only as a comparison base. It tells you what the team is said to pay in a normal year; it does not tell you what the team would owe to leave. When you see the rent and the break estimate in the same sentence, separate them immediately: one is recurring, the other is contingent. Your check is to find the rent line in the lease or an official financial exhibit, then confirm the same figure in a second source before using it in any comparison.
The third item is not a dollar figure but a timeline marker. In early 2023, Churchill Downs, owner of Arlington International Racecourse, said the sale to the Bears could proceed, according to the period’s reporting. That matters because it explains why the break-cost question became practical rather than theoretical: once a potential new-site path was publicly discussed, the exit number became the constraint to test. But a seller’s statement about a possible sale is not proof of a finalized stadium plan, and it is not proof of what the Park District would charge to release the Bears from their existing obligations.
Subsequent Tribune coverage added an important qualification: the break cost “doesn’t seem as prohibitive as once thought.” That wording is a signal, not a substitute for documentation. It suggests the real penalty may be materially below the $90M headline, but it does not identify the controlling figure by itself. The verification step is narrow: locate the lease amendment or board minutes, find the provision governing early termination or any negotiated release, and check whether the amount, formula, or payment schedule matches the reported estimate.
Use the three figures as a source-checking sequence. Start with the nearly $90M Tribune estimate, confirm the reported $6.5M annual rent, then place the early-2023 Arlington/Churchill Downs sale statement alongside them as context for why the exit question moved forward. If two independent reports agree but the official lease document is silent or unavailable, label the figure as reported rather than settled. The decision math depends on the break cost, so the burden of proof belongs on the exit number, not on the rent.
Stay vs. Exercise vs. Break: Compared
The Bears’ 2026 Soldier Field decision can be compared across three paths: exercise the option year, break the lease, or renegotiate. Each path carries a different cost profile and a different effect on the team’s leverage, so the practical question is which option best preserves flexibility until the governing numbers are confirmed.
| Option | Reported immediate cost | Strategic effect | Rational when |
|---|---|---|---|
| Exercise the 2026 option year | Annual rent reported at about $6.5 million (unverified) | Preserves flexibility for one more year while Arlington Heights entitlements mature | The reported rent remains far below any confirmed break penalty |
| Break the lease | Penalty once estimated near $90 million, but reported as possibly lower (unverified) | Ends the current commitment immediately but requires a large, confirmed cash outlay | The true penalty is verified well below the headline estimate |
| Renegotiate | No direct cash payment | Concedes leverage, since the Arlington Heights purchase removed the Bears’ need to stay | Revised terms provide clear value that offsets the weaker negotiating position |
On the reported figures alone — and only on those figures — exercising the 2026 option year looks like the leading path: the reported ~$6.5M annual rent is a limited, one-year commitment, whereas the once-estimated penalty near $90M would impose a substantially larger immediate cost. But because neither number has been confirmed against the lease documents, this is a scenario ranking, not a conclusion. The option year preserves flexibility while Arlington Heights entitlements mature and avoids committing to a break decision based on an unconfirmed figure; the ranking must be re-run once the verified penalty and rent are in hand.
Breaking the lease becomes defensible only if the actual penalty, confirmed in the governing documents, comes in well below the headline estimate. Renegotiation may appear attractive because it requires no direct cash payment, but it asks the Bears to bargain from a softer position after securing an alternative site. In both cases, the apparent upside depends less on headline figures than on what the verified terms actually allow.
Before treating any lease figure as settled, pull the actual Chicago Park District lease amendment or board minutes and verify the rent, option terms, and break penalty against at least two independent reports. Re-run this three-way comparison against those confirmed figures, because the preferred path can change if the documented penalty differs materially from what has been publicly reported.
The Break-Cost Arithmetic That Matters
The arithmetic that actually governs the 2026 decision is a ratio, not a line item: break penalty divided by annual rent gives the break-even horizon. Using the figures already on the table — a reported ~$6.5M annual rent and a break estimate once put near ~$90M — that division works out to roughly 13.8 years ($90M ÷ $6.5M ≈ 13.846). Read plainly, breaking only wins if an alternative venue produces more than ~$90M in net incremental value inside that span. Below that threshold, staying is the cheaper path on these numbers alone.
That framing matters because the rent is the recurring cost you keep paying, while the penalty is the one-time cost you either trigger or avoid. A team comparing options can easily fixate on the yearly check and miss that the exit charge is what sets the clock. The worked example above is the whole test: if the alternative generates net value at a pace below the implied annual hurdle, the break never catches up within the horizon the penalty buys you.
Before you trust that 13.8-year result, confirm the penalty formula itself. A flat buyout, an obligation to pay out remaining rent, and a declining schedule each produce a different break-even horizon, so the same headline number can mean very different exposure. Pull the actual Chicago Park District lease amendment or board minutes and read the clause that defines the exit payment; then verify what you find against at least two independent reports. If the clause is a remaining-rent obligation rather than a flat sum, the effective cost changes with how much term is left, and the simple division above no longer describes the decision.
Run the second check on the rent input. The ~$6.5M figure is reported, but if the executed document puts annual rent higher — say $10M — the same ~$90M penalty divides to about 9 years instead of 13.8. A higher rent shortens the horizon and makes breaking easier to justify; a lower rent lengthens it and strengthens the case to stay. Either way, recompute the ratio from the document rather than carrying the reported figure into the model untested.
Treat both inputs as variables until the source documents settle them. The rule is simple: verify the penalty structure, verify the rent, recompute the quotient, and only then compare it with the alternative venue's projected net value. Until those checks are done, the 13.8-year figure is a worked illustration of the method — not a finding about what the Bears should do in 2026.
What the Reporting Does Not Establish
This section catalogs the unverified terms that sit underneath the 2026 stay-or-go math: the exact $6.5M figure, the option exercise deadline, and the current penalty schedule. Each one is reported or assumed in secondary discussion, and each one needs to be pulled from the underlying document before it can carry any weight in a decision. The practical rule is simple: treat every lease number as provisional until you have the amendment or the board minutes in front of you and at least two independent references that say the same thing.
The $6.5M annual rent figure is the clearest example. It appears in reporting and in the arguments built around that reporting, but it is not confirmed here against the lease text itself. Before using it as the baseline for a comparison, request the amended lease through the Chicago Park District’s records process or search the Park District board records for the amendment and the accompanying staff materials. The check is not whether a second article repeats the number; it is whether the executed document, or an official board record adopting it, states the rent and the years to which it applies.
The option exercise deadline is a second term that the reporting does not establish. The lease’s notice provision is the controlling text, and it should be read for the required lead time before the option year and for the form of notice the Park District will accept. A missed notice window can turn what looks like a $6.5M annual decision into a default, so the deadline should be treated as an affirmative calendar item, not as background. If the provision is unclear, the working check is to confirm the notice date in writing with the Park District and then verify that date against the board-approved lease documents.
The penalty schedule deserves the same treatment. The roughly $90M break estimate is widely discussed, but this section does not establish whether that figure reflects the current amended penalty or an earlier version of the agreement. The document check is to compare the executed amendment with the original lease terms and any later board action that changed the break provisions. If the amendment restates or replaces the penalty language, the restated schedule controls the analysis; if it does not, the earlier estimate should be labeled as an estimate rather than a current contractual amount.
These checks matter because the rent and the break cost do different work. Rent is the recurring number people notice, while the break cost is the number that can determine whether leaving is financially rational at all. That is why the break figure, not the annual rent, drives the stay-or-go math. But a break figure is only as reliable as the amendment behind it. Until the current penalty schedule is verified, any comparison built on it is a scenario, not a conclusion.
As established in the verification rule above, hold every figure as reported rather than settled until the executed amendment and a corroborating board record agree. If two sources disagree, do not average them or choose the more convenient one; go back to the executed amendment and the board action. That discipline keeps the reported rent, the option deadline, and the penalty schedule from being treated as settled when the available reporting has not made them settled.
Your Verification Checklist and Decision Rules
This section is the copy-usable lease-verification worksheet and the if/then rules for acting on it. Use it before you treat any figure as settled. The worksheet has five rows, and every row needs a source citation back to the actual Park District lease amendment or board minutes, plus confirmation against at least two independent reports. Do not fill a row from a single news mention, a fan post, or a summary that repeats itself.
Worked example using the article's reported (unverified) figures: row one, annual rent entered as ~$6.5M pending confirmation in the lease text; row two, break penalty entered as the Tribune-reported estimate of nearly $90M, pending confirmation of the actual formula; row three, the option notice deadline left open until the lease's notice provision is pulled; row four, remaining term of one option year (2026); row five, break-even computed as $90M ÷ $6.5M ≈ 13.8 rent-years. That last row is the one that turns the paperwork into a decision, because it converts a lump-sum exit cost into the number of rent years the penalty represents — but every input stays provisional until the executed amendment confirms it.
Now apply decision rules to the verified worksheet, treating the bands as illustrative thresholds rather than sourced terms. IF the verified penalty exceeds roughly 5× annual rent (on the reported figures, $90M against ~$6.5M is about 13.8×), THEN exercise the option year and revisit next cycle — the exit premium is not worth paying early. IF the verified penalty falls well below 2× annual rent, THEN breaking is cheap optionality and the lease is not a real constraint. Between those bands, slow down: recheck the formula, confirm the notice deadline, and make sure the remaining term matches the option year you are actually deciding on.
Arithmetic discipline matters here. Divide the penalty by the rent digit by digit, then sanity-check the result against the remaining term. If the quotient is longer than the term left on the lease, the penalty is not a near-term exit price; if it is shorter, the exit cost can be absorbed within the term you are already committed to. Either way, the comparison only holds if rows one and two came from the same executed document, not from two different reporting cycles.
Keep the worksheet attached to the board minutes you pulled, and date each verification. When a later report revises a figure, replace the row and recompute row five before applying either rule. That habit keeps the stay-or-go math tied to the verified break cost rather than to whichever rent number happens to be circulating in the current cycle.
Frequently Asked Questions
Who has to approve a Bears stadium renegotiation, extension, or exit tied to the premises?
A renegotiation, an extension, or an exit tied to the stadium premises is a Park District board action, not a City Council vote.
Why should a report saying the city and the Bears are working out terms be treated cautiously?
If you see a report framed as "the city and the Bears" working out terms, treat that as shorthand until you find the amendment or board minutes naming the Park District as the party acting.
How can a reader verify which party is actually acting on a stadium lease change?
Pull the document, read the signature block and the approving body, and match the actor to the remedy.
What does an option year give the Bears before the 2026 decision?
An option year is a unilateral extension right: the tenant can lock an additional year at pre-set terms without reopening the whole deal.
Why does the exercise date matter more than the base term in coverage of the 2026 decision?
The base term tells you where the team currently stands, while the option tells you whether the team can hold that position without a fresh bargain.
What should be checked in the clause governing the option year?
Look for the clause that says who may exercise, what form the notice takes, and whether the terms are fixed by the existing instrument or subject to later agreement.
Quick answers
| Who is the counterparty in the Bears' stadium arrangement? | The Bears' stadium arrangement runs through the Chicago Park District, not the City of Chicago. |
| What kind of action is a renegotiation, extension, or exit tied to the stadium premises? | A renegotiation, an extension, or an exit tied to the stadium premises is a Park District board action, not a City Council vote. |
| How should reports framed as "the city and the Bears" working out terms be treated? | If you see a report framed as "the city and the Bears" working out terms, treat that as shorthand until you find the amendment or board minutes naming the Park District as the party acting. |
| What is an option year? | An option year is a unilateral extension right: the tenant can lock an additional year at pre-set terms without reopening the whole deal. |
| Why does the exercise date carry more weight than the base term in coverage of the 2026 decision? | That is why the exercise date carries more weight than the base term in coverage of the 2026 decision: the base term tells you where the team currently stands, while the option tells you whether the team can hold that position without a fresh bargain. |
Also worth reading: Chicago Bears stadium plans take shape in lakefront proposal: Chicago Bears stadium plans take · Seedamm Plaza 2025: Traffic-to-Rent Conversion via 42 Beacons: Seedamm Plaza 2025: Traffic-to-Rent Conversion · Harrison PATH Redesign: 15% Transfer Cut, Rent Premium as Capital: Harrison PATH Redesign: 15% Transfer